Robin Powell is a freelance journalist and author, and a financial consumer advocate. He is also the editor of The Evidence-Based Investor.
Published
This article is general information, not a personal recommendation. Pension and tax rules can change, and suitability depends on your circumstances.
Advice firms are changing hands at a striking pace. If yours has been sold, your protections stay in place. The moment that matters may come later, if the new owner suggests moving your money.
When you chose your financial adviser, you probably didn't think much about who owned the firm. You chose a person.
Perhaps a friend recommended them. Perhaps you've sat across the table from them for 15 years. They know your plans for retirement, your children's names and what keeps you awake at night.
So it can come as a jolt to learn that the firm has been sold. Nothing seems different yet. The same person may still answer the phone. But there's a new name above theirs now, and it's natural to wonder what that means for you and your money.
You're far from alone in asking that. And for most people, the moment that really matters comes a little later.
Why so many advice firms are changing hands
If this has happened to you, you're part of a much bigger shift. Many UK advice firms are small, and running one has become steadily more expensive. Advisers point to rising regulatory costs, the price of insurance, new technology and the difficulty of hiring good staff. Plenty of founders are also nearing retirement themselves, with no obvious successor.
Bigger groups have stepped in to buy these firms. Some are backed by private equity: investors who buy businesses, aim to grow them and often sell them on after several years. Others are banks and established wealth managers.
The pace has been striking. According to analysis by Citywire, reported in The Times, the number of advisers working at private equity-backed firms rose from 4,157 in 2023 to 7,706 by March 2026.
The Financial Conduct Authority, the City regulator, looked closely at this trend in a review published in October 2025. It found real benefits. Bigger groups can pool expertise and be more financially resilient. But it also flagged risks for clients.
What stays the same
Before we get to those, the reassuring part.
A change of owner doesn't weaken your protection. The firm advising you must still be authorised by the FCA, and the Financial Services Compensation Scheme (FSCS) still applies, within its usual limits. Your pension and investments don't move anywhere on their own.
The new firm can't simply carry on as though nothing has happened, either. The FCA expects a firm that takes on another firm's clients to get their agreement before it provides or charges for its services.
In short, your money stays as it is unless you agree to a change. That brings us to the moment you might be asked to.
The letter that matters most
The letter announcing the sale is usually the easy one to read. The one worth reading slowly may arrive months later, suggesting you move your money.
Why would a new owner want to move it? Partly because of how many of these groups make money. They charge for advice, of course. But many also run their own investment funds, or their own platform, the online service that holds your investments. When clients' money sits there, the group earns more than it would from advice alone.
Daniel Baade, who advises on deals in the sector, told Citywire that, commercially, private equity owners would like as much money as possible in their own investments. But he added that this is only acceptable where it's in clients' best interests.
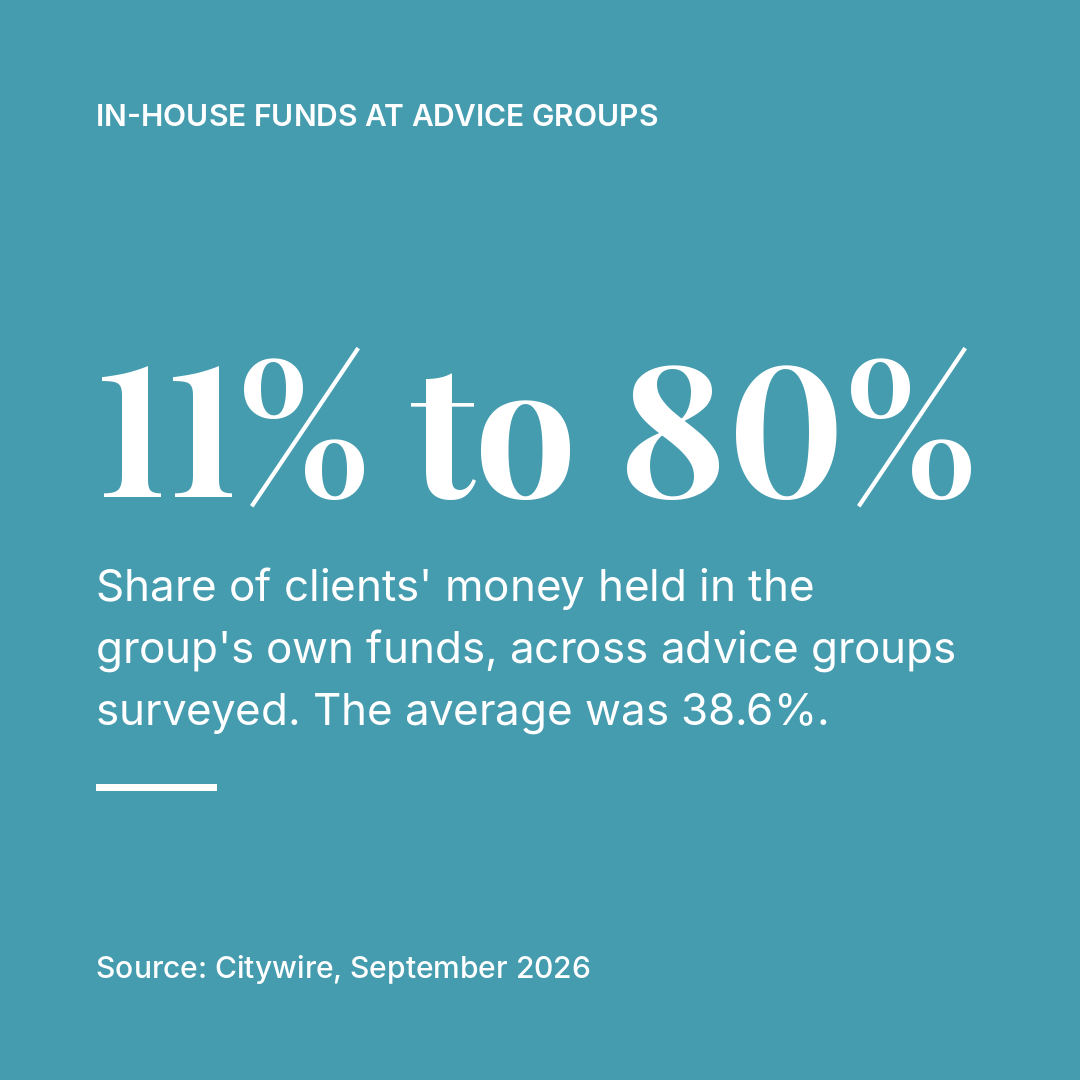
How likely you are to be asked to move depends a great deal on who bought your adviser's firm. Among the groups that gave Citywire figures, the share of clients' money held in the group's own funds ranged from 11 per cent to 80 per cent. The average was just under 40 per cent.
Image
The FCA's review also found some groups offering incentives, direct or indirect, that could steer clients towards the group's own products.
None of this means a suggested move is wrong. A bigger group may offer a perfectly good way of investing. But a move can also change the whole approach behind your investments, which might become more cautious or more adventurous than before. That deserves a proper conversation.
Questions worth asking before you agree
If a new firm suggests moving your money, these questions can help you understand what's being proposed.
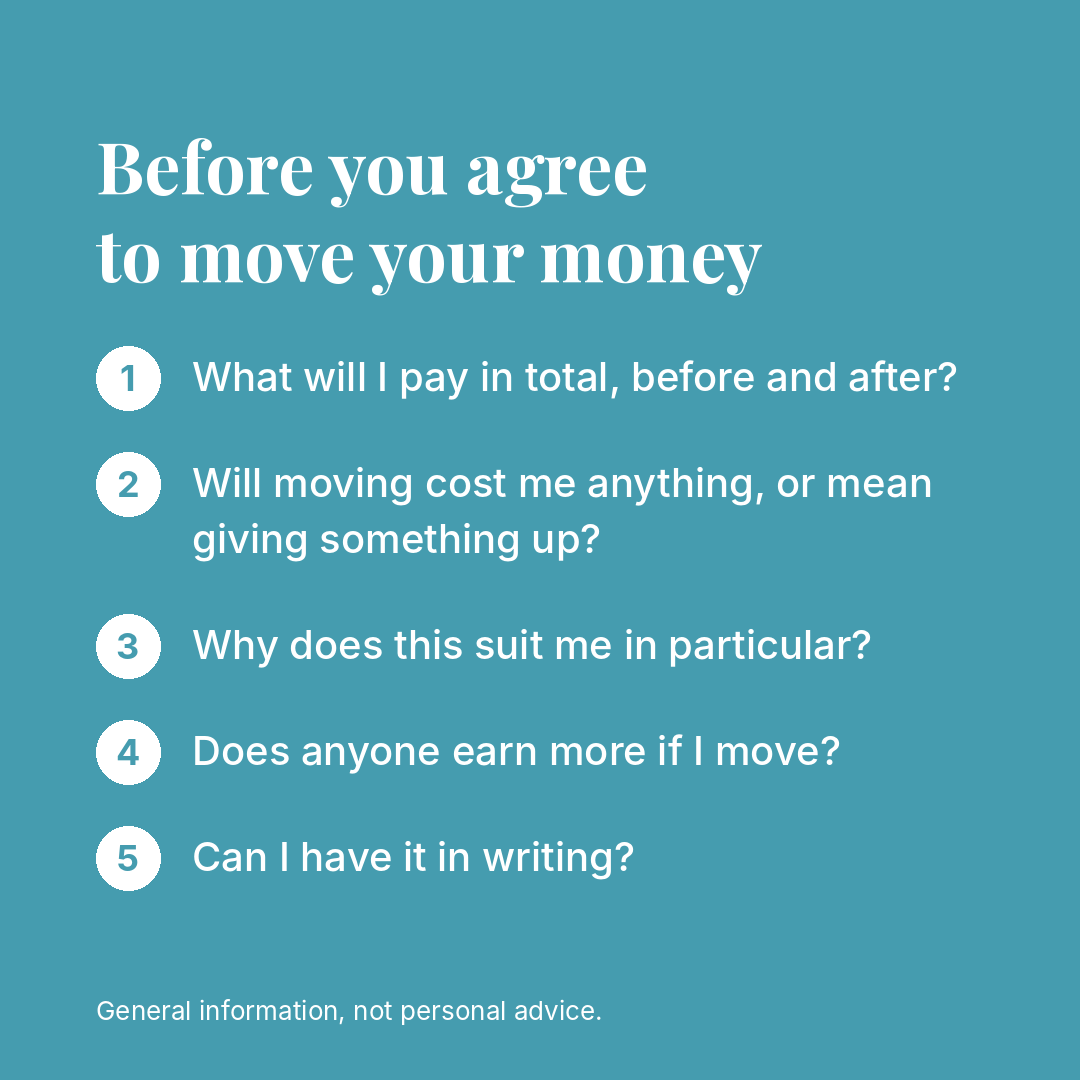
Will moving cost me anything, or mean giving something up? Some older pensions and investments have exit charges or valuable guarantees, and selling investments can sometimes have tax consequences.
Why does this suit me in particular? A good recommendation explains how the new arrangement fits your circumstances and plans, and how your money would be invested differently.
Does anyone earn more if I move? It's a fair question, and a good adviser won't mind you asking it.
Can I have it in writing? A recommendation with the costs compared side by side gives you something to take away and think about.
These questions aren't only for people whose adviser has been bought out. They're worth asking whenever anyone suggests moving your pension, whether that's a new owner, your provider as you approach retirement, or an adviser such as Pense.
Image
Your decision, in your own time
You don't have to decide straight away. You can ask for more information, take time to think, say no, or get a second opinion from another adviser.
It's also worth remembering that good advice doesn't always mean change. Pense's advisers, for instance, can recommend doing nothing at all if that's the right outcome for the client.
What's right for you depends on your circumstances. But if your adviser's firm has been sold, you now know which letter to read slowly, and what to ask when it arrives.
Robin Powell is a journalist, author and financial consumer advocate, and is editor of The Evidence-Based Investor
Pensions and inheritance tax: what changes in 2027, and what it means for you
Perhaps you saw a headline. Perhaps someone mentioned it at the golf club, or your daughter sent you a link. From April 2027, the money left in your pension when you die will count towards inheritance tax.
Can you change your mind after making a pension decision? In this video, Robin explains which pension choices are typically irreversible, which may offer some flexibility, and why understanding the implications before you act is so important.
Think about the bills you've paid this year. The energy company sends a statement. The phone company takes a direct debit. Even your bank, if it charges you, shows the fee on your statement.